debt consolidation

Home » debt consolidation
Skip to main content

Welcome to Sucredit

Home » debt consolidation
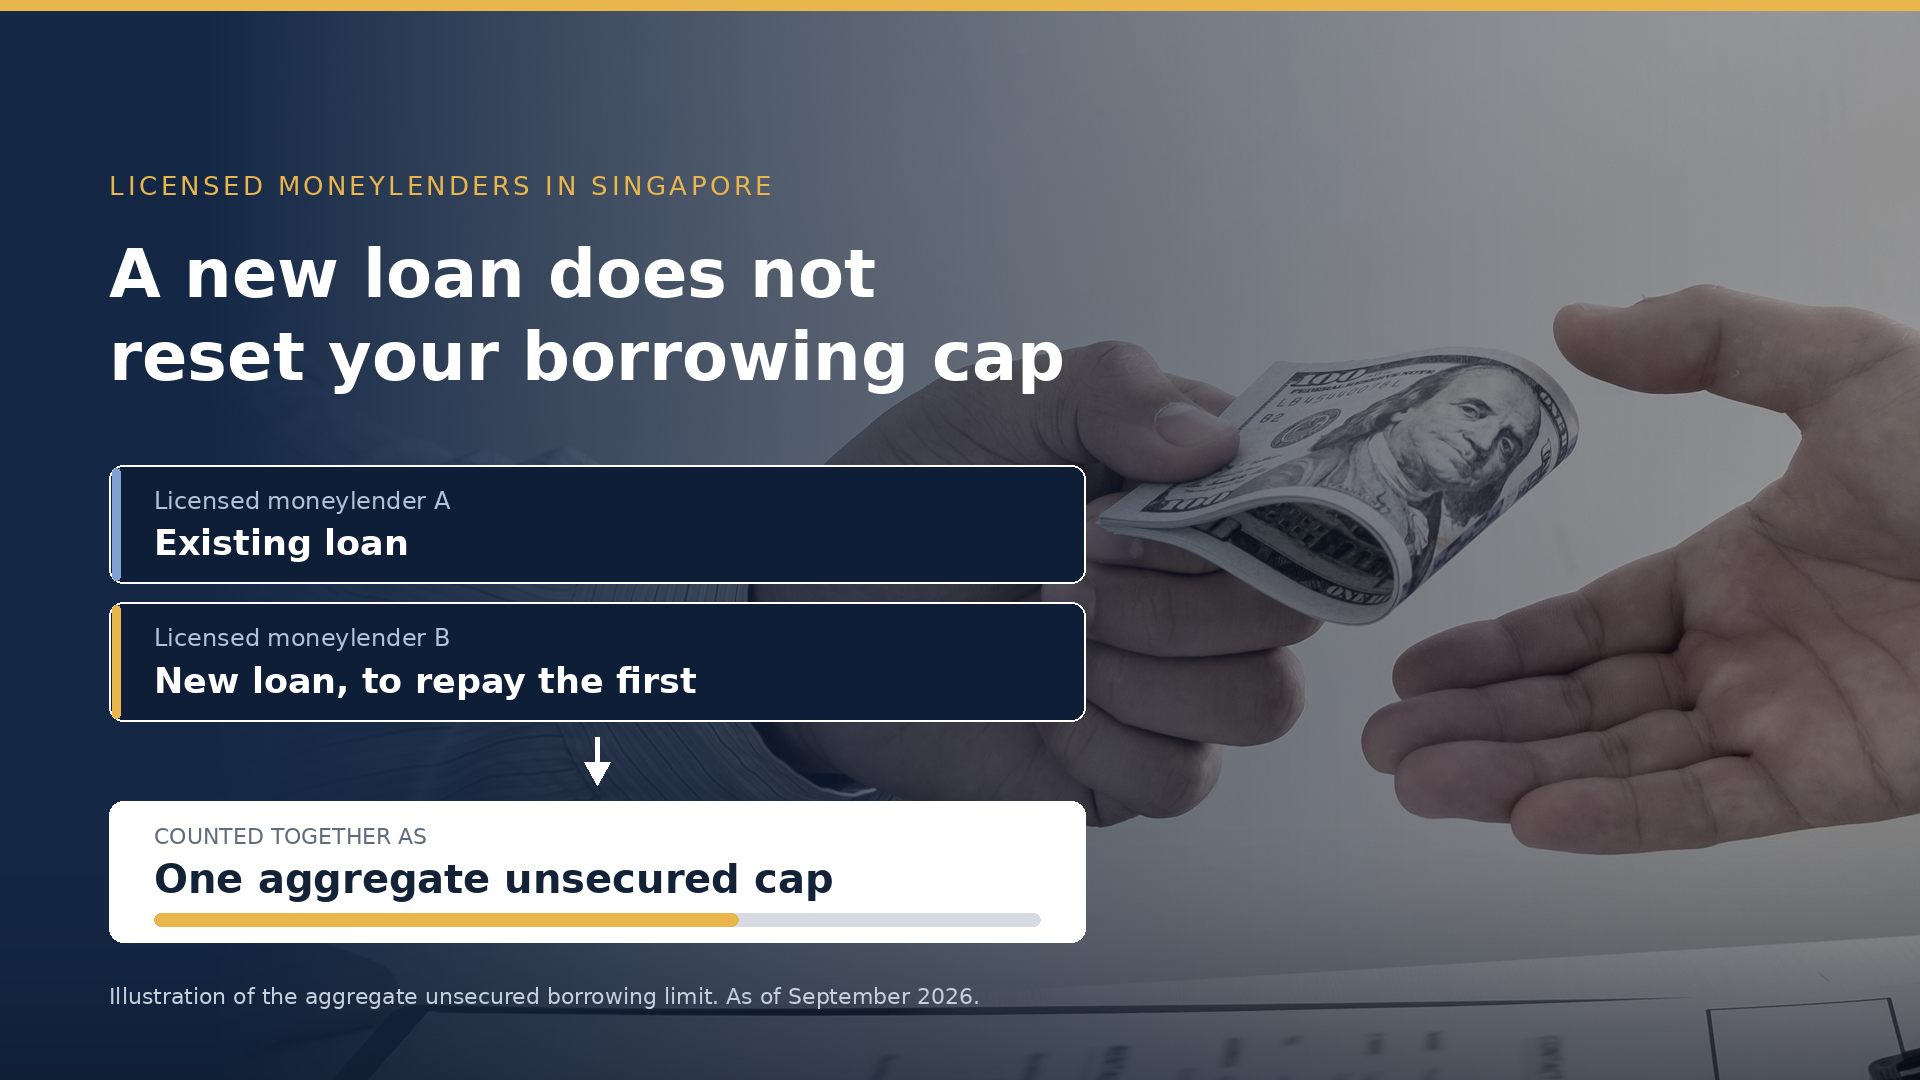
Hero banner showing a borrowing-themed scene: hands exchanging money with the headline 'A new loan does not reset your borrowing cap' and two loan option panels below.
debt consolidation

Can You Take a New Moneylender Loan to Pay Off an Existing Loan?

Yes. There is no blanket prohibition in Singapore on using a loan from a licensed moneylender to repay another licensed moneylender’s loan — the debt consolidation scheme is built around that purpose. What a new loan does not do is give you a fresh borrowing limit. And as of September 2026, the Registrar’s Directions specifically tell licensees not to use a re-loan from the same lender to reset your borrowing cost. Here is how the limits, the cost, and the rules work. Can you take a new moneylender loan to pay off an existing loan? Yes, subject to the borrowing limits. Licensed moneylenders in Singapore can lend you money that you then use to repay an existing loan, and the Ministry of Law’s debt consolidation scheme is defined around exactly that purpose. What does not change is the ceiling: everything you owe across all licensed moneylenders counts towards one aggregate cap. Approval is subject to the lender’s assessment of your income, existing loans, and repayment ability. Is it legal in Singapore to borrow from one licensed moneylender to repay another? Yes, and the regulatory framework contemplates it. The Registry of Moneylenders’ Professional Service Handbook for Licensed Moneylenders (Version 3.1, dated 13 August 2026) defines a debt consolidation loan as “a loan granted by a licensed moneylender under the debt consolidation scheme to a borrower for the purpose of enabling the borrower to repay all outstanding debts owed by the borrower to all licensed moneylenders”. There is no blanket ban. What still applies are the aggregate borrowing limits, the lender’s assessment, the rules on excluded persons, and the restriction on same-lender re-loans set out next. Can the same moneylender give you a new loan to clear the one you already owe them? Not where it resets your borrowing cost. Registrar’s Directions No. 1 of 2026, effective 1 April 2026, state that licensees “should not grant loans or ‘re-loans’ to borrowers to reduce or extinguish an existing debt owed to the same licensee such that this serves to ‘reset’ the total borrowing cost charged, as this is tantamount to deliberately circumventing rules 11, 12 and 12A of the Moneylenders Rules 2009”. Paragraph 1.3 of the same Directions lists as an undesirable practice “offering loans or ‘re-loans’ to pay off existing loans when borrowers are unable to fully pay sums that are due, and charging the borrowers a 10% ‘administrative fee’ repeatedly to roll over the existing loan”. Genuine loan restructuring that complies with the Moneylenders Rules 2009 is still permitted. But the Directions state that these practices may be grounds for refusing a licence renewal, or for suspending or revoking a licence. If a lender offers to clear your existing loan with them by writing a new one that starts the cost over, that is the arrangement the Directions target. Ask about restructuring instead. How much can you borrow if you already have outstanding moneylender loans? As of September 2026, the unsecured borrowing cap for licensed moneylender loans in Singapore is an aggregate figure — it applies to everything you owe across all licensed moneylenders combined, not to each lender separately. A Singapore Citizen or PR earning below S$20,000 a year can borrow up to S$3,000 in total. At S$20,000 or more, the cap is six times monthly income. Existing outstanding unsecured principal counts towards it. Unsecured borrowing caps, aggregate across all licensed moneylenders (as of September 2026) Annual income Singapore Citizens and PRs Foreigners residing in Singapore Below S$10,000 S$3,000 S$500 S$10,000 to below S$20,000 S$3,000 S$3,000 S$20,000 or more 6 × monthly income 6 × monthly income For secured loans, the Registry of Moneylenders states you can obtain a loan of any amount. Your existing loans are visible through the Moneylenders Credit Bureau (MLCB), operated by Credit Bureau (Singapore) Pte Ltd as the designated credit bureau, which a licensed moneylender checks when assessing an application. Source: Registry of Moneylenders, FAQs on Borrowing From Licensed Moneylenders. If I’ve joined the MLCB self-exclusion scheme, can I still take a loan to repay my existing one? Generally no, with one exception. Self-exclusion is a voluntary scheme through the MLCB. Singapore Citizens and PRs may choose a minimum period of 1 or 2 years; foreigners have a minimum of 2 years. While you are registered, you generally cannot obtain unsecured loans from licensed moneylenders, except for a debt consolidation loan. What would a new loan to repay an old one actually cost you? As of September 2026, licensed moneylenders in Singapore may charge at most 4% interest per month on the outstanding principal, and at most 10% of the principal as an administrative fee when the loan is granted. Late interest is capped at 4% per month on the overdue amount, plus a fee of at most S$60 for each month of late repayment. These are legal maximums, not the rate any lender quotes. One further limit matters here: total charges — interest, late interest, the administrative fee and late fees combined — cannot exceed the principal. How is 4% monthly interest worked out on a balance that shrinks as I repay? Interest is charged on what is still outstanding, so it falls as the principal comes down. Illustration only, using the legal maximum rate on an S$3,000 loan repaid in six monthly principal instalments of S$500: Month 1: S$3,000 outstanding, interest S$120 Month 2: S$2,500 outstanding, interest S$100 Month 3: S$2,000 outstanding, interest S$80 Month 4: S$1,500 outstanding, interest S$60 Month 5: S$1,000 outstanding, interest S$40 Month 6: S$500 outstanding, interest S$20 Total interest: S$420. Add an administrative fee of up to 10% of the principal at grant (S$300), and borrowing S$3,000 costs up to S$720. This is an illustration calculated from the statutory maximums — not a SuCredit product or quotation. Do I pay the administrative fee again on the new loan? As of September 2026, a licensed moneylender in Singapore may charge an administrative fee of up to 10% of the principal when a loan is granted, so a new
Close-up view of the words "DEBTS HELP ME" arranged on a scramble board with glowing lights in the background, symbolizing the urgent need for a debt consolidation plan in Singapore.
debt consolidation

Debt Consolidation Plan in Singapore: A Comprehensive Guide

Are you feeling overwhelmed by credit card debt in Singapore? The debt consolidation plan in Singapore might be the relief you need. With enticing credit card rewards like air miles, cash back, and even free luggage, it’s easy to find yourself swiping away without considering the consequences. However, this convenience often leads to a daunting pile of debt. If you’re struggling to keep up with credit card and personal loan payments, a Debt Consolidation Plan could be your pathway out of financial stress. This guide will explore how such a plan works and how it can help you regain control of your finances. What Is a Debt Consolidation Plan in Singapore? A Debt Consolidation Plan in Singapore allows individuals to consolidate all their outstanding unsecured loans into a single loan from a financial institution, such as a licensed money lender or bank. This approach simplifies debt management by reducing multiple payments to just one monthly repayment, making it easier to manage finances. Key Features Interest Rates: While the interest rates for DCPs may seem high compared to other loan types, they are significantly lower than the average credit card rates in Singapore. The credit card rates can be as high as 25% per annum. DCPs generally offer rates between 3.12% and 12%. This makes DCPs an advantageous option for those struggling with high-interest credit card debt and other unsecured loans. Loan Amount: The Debt Consolidation Plan allows you to borrow an amount ranging from 12 to 18 times your monthly salary. This flexibility ensures that you can consolidate a significant amount of debt under one loan. This is especially helpful if you have multiple high-interest loans or credit card debts. Repayment Tenure: The plan offers flexible repayment options, with terms ranging from 1 to 10 years. This range allows you to choose a repayment period that best suits your financial situation and goals. Thus, it makes easier to manage monthly payments without overstressing your budget. By consolidating debts, individuals can avoid the compound interest that quickly accumulates on credit cards, often referred to as the “snowball effect.” This helps in managing debt more effectively and can prevent the debt from growing uncontrollably. As a licensed money lender in Singapore, SU Credit provides options for those considering a debt consolidation plan. We offer guidance and services to help individuals consolidate their debts, thereby gaining better control over their financial situation. How the Debt Consolidation Plan in Singapore Works? Imagine you’re earning a monthly salary of S$3,000 but have accumulated debts totaling S$80,000 due to multiple credit card and personal loan expenses on luxury items. This amount is well over 12 times your monthly income, indicating a significant financial strain. In this situation, a debt consolidation plan in Singapore could be a strategic move. By consolidating all your high-interest debts into one loan with a lower interest rate from a financial institution, you reduce your monthly burden. Instead of multiple payments, you make a single repayment to the institution that now holds your consolidated loan. This plan simplifies your finances and potentially lowers the amount you pay monthly. For those not eligible or looking for different options, alternative personal loans like balance transfers or personal installment loans might be suitable. Loan Exclusions in Debt Consolidation Plans in Singapore In Singapore, Debt Consolidation Plans (DCPs) are specifically helpful for managing unsecured loans like personal installment loans, credit card debts, and personal lines of credit. These types of debts do not require collateral to be provided by the borrower. However, secured loans, which are backed by assets like property for property loans, vehicles for car loans, or funds for education loans, cannot be included in a DCP. Business loans also do not qualify for consolidation under a DCP. This exclusion of secured and business loans helps to focus the DCP on high-interest, unsecured debts, making it a targeted solution for personal financial restructuring. Eligibility for Debt Consolidation Plan in Singapore The Debt Consolidation Plan (DCP) is for Singaporeans and permanent residents. This ensures that the program supports local citizens and residents in managing their debts. Income and Asset Criteria Applicants must have an annual income ranging from S$20,000 to S$120,000. Moreover, their net assets should not exceed S$2 million. These criteria help to target the DCP towards individuals who are neither too wealthy nor below a certain income threshold. Debt Requirements To qualify for a DCP, you must be facing significant debt levels—specifically, your total debts must be at least 12 times your monthly income. This condition confirms that the DCP caters those who have heavy debts to pay and are truly in need of assistance in debt management. SU Credit can assist eligible individuals by offering DCPs as part of their financial solutions, providing a structured approach to managing and reducing their debt burdens efficiently. For more detailed guidance and to see if you qualify for a DCP, consulting with licensed money lenders like SU Credit can be very helpful. Documents Required For the Application To apply for a Debt Consolidation Plan, you will need to prepare the following documents: Credit Bureau Report NRIC (front and back) Latest income statements Recent statements for credit cards and other unsecured credits, such as personal loans If applicable, confirmation letters detailing unbilled principal balances for unsecured installment plans These documents help verify your identity, financial status, and the extent of your debts, ensuring a smooth application process. What to Consider Before Applying for a Debt Consolidation Plan in Singapore? Understanding Additional Charges When you get a Debt Consolidation Plan (DCP) in Singapore, your loan amount will include not just your current debts and outstanding interest, but also an extra 5% above this total. This additional percentage covers potential fees like late payment charges that might occur during the repayment period. Rest assured, any excess from this buffer will be returned to you at the end of the loan term. Refinancing Options If you decide that you want to switch your DCP to another financial institution,

Debt Consolidation Benefits Singapore
debt consolidation

Boost Your Credit: Singapore’s Debt Consolidation Benefits

In today’s busy world, managing your finances can feel overwhelming, especially in Singapore’s fast-moving economy. Debt consolidation is becoming popular for anyone looking to manage their financial obligations. It’s beneficial for young professionals who want to improve their credit scores. Combining multiple debts into one manageable loan can simplify your payments and even open the door to better opportunities, like qualifying for a housing loan or getting approved for a credit card. Understanding Debt Consolidation Debt consolidation combines several unsecured debts—such as credit card balances, personal loans, and other liabilities—into a single loan with a unified monthly payment. This strategy can simplify debt management, reducing the stress of managing multiple due dates and interest rates. Essentially, a debt consolidation loan allows borrowers to focus on one payment, often with a fixed interest rate, which can be more predictable than juggling various debt obligations. The goal is to simplify payments, potentially lower the overall interest rate, and ultimately make it easier to pay off the total debt over time. Benefits of Debt Consolidation in Singapore One of the primary advantages of debt consolidation in Singapore is the potential to lower interest rates and monthly payments. With a consolidated loan, you may negotiate a better interest rate than the higher rates typically associated with credit cards and other unsecured debts. This can mean significant monthly savings for young professionals, freeing up cash for other essential expenses or investments. Moreover, consolidating debts can have a positive impact on your credit score. By reducing the number of outstanding accounts and ensuring timely payments, your credit profile can improve, opening doors to more favorable financial opportunities.  Additionally, the convenience of handling a single payment instead of multiple ones can lead to greater peace of mind. This streamlined approach alleviates the mental burden of managing numerous debts and minimizes the risk of missed payments, which can adversely affect credit scores. How to Apply for a Debt Consolidation Loan in Singapore Applying for a debt consolidation loan in Singapore is straightforward. It is designed to assist borrowers in taking control of their financial obligations. The first step is to gather all relevant documents, including proof of income, existing debt statements, and credit history reports. These documents are essential for lenders to assess your financial situation accurately. Once your documentation is in order, research and compare financial institutions offering debt consolidation loans. Each lender may have varied terms and interest rates, so finding one that aligns with your financial goals is crucial. After selecting a suitable lender, complete their application process, which typically involves filling out forms and submitting the necessary documents. Once approved, the lender will disburse funds to pay off your debts, consolidating them into a single loan. Eligibility Criteria You must meet specific eligibility criteria to qualify for a debt consolidation loan in Singapore. Lenders generally require applicants to be Singaporean citizens or permanent residents aged between 21 and 65. A stable income is also crucial, as it assures the lender of your ability to repay the loan. This often means having a minimum income threshold, which varies among lenders. Your existing debt levels and credit history significantly influence the approval process. Lenders will assess your debt-to-income ratio to ensure the new loan will not overextend your financial capabilities. Maintaining a good credit score is also essential, as it increases your chances of securing favorable loan terms. Therefore, reviewing your credit report and rectifying any discrepancies before applying is advisable. Potential Drawbacks While debt consolidation offers numerous benefits, potential drawbacks should be considered. One possible downside is that extending the loan term to achieve lower monthly payments might result in paying more in interest over the life of the loan. Additionally, consolidating debts without addressing underlying spending habits could lead to further financial challenges. Understanding the long-term implications of taking on a debt consolidation loan is crucial. Ensure that the terms align with your financial strategy and that you are committed to disciplined financial management. Consulting with a financial advisor can provide valuable insights specific to your situation. To Wrap It Up Debt consolidation can be a powerful tool for boosting credit and achieving financial stability, especially for Singapore’s young professionals. Individuals can lower interest rates, simplify payments, and enhance their credit profiles by consolidating debts. When approached thoughtfully, debt consolidation loans in Singapore offer a strategic pathway toward financial empowerment. Consider exploring this option to navigate your financial journey with confidence and poise.

Su Credit, 175 Bencoolen Street #01-36 Burlington Square, Singapore, 189649 Tel: +65 6636 5644