Tahsin Islam

Home » Tahsin Islam
Skip to main content

Welcome to Sucredit

Two businesswomen shake hands on a city balcony beside a teal gradient banner reading 'Leaving Singapore With a Loan?'
loan for foreigners in Singapore

Leaving Singapore or Changing Jobs With a Moneylender Loan: What Work Pass Holders Need to Know

Leaving Singapore does not cancel a loan from a licensed moneylender. You remain legally obliged to fulfill the loan contract, and the lender can take legal action to recover what you owe. The law also limits what you can be charged: as of September 2026, interest, late interest and fees together can never exceed the amount you borrowed. If your job or work pass is ending, speak to your lender before your last working day. This guide is for Work Permit, S Pass and Employment Pass holders whose job is changing or ending while a loan is still being repaid. A loan from a licensed moneylender stays in force when you leave Singapore A loan from a licensed moneylender in Singapore does not end when you leave the country. The Registry of Moneylenders states that borrowers are legally obliged to fulfill any loan contract they enter into, and the borrower rules make no exception for moving overseas. A licensed moneylender may take reasonable steps to recover the debt, including contacting you and taking legal action to enforce the contract. Ordinary non-payment of a licensed moneylender loan is a civil debt matter, not a criminal offense in itself, although separate offenses can arise from other conduct. That is not permission to walk away. The debt remains, and so does the lender’s right to pursue it through the courts. The caps on what you can be charged stay with the loan too. They are set in the Moneylenders Rules, made under the Moneylenders Act 2008, and do not depend on where you live. Moneylender loans and bank debts sit in separate credit systems Licensed moneylenders in Singapore must submit loan and repayment information to the Moneylenders Credit Bureau (MLCB), the central record for licensed moneylending. Banks and credit card companies share their customers’ borrowing information with credit bureaus such as Credit Bureau Singapore (CBS). If you have both kinds of debt, each is recorded in its own system. Changing jobs or losing your work pass does not rewrite your loan A change of job, a lower salary or a cancelled work pass does not, by itself, automatically rewrite an existing loan agreement with a licensed moneylender in Singapore. Your installments stay as set out in your contract. Income is specifically relevant when a new unsecured loan application is assessed. If you are unsure whether to tell your lender about a new employer or new contact details, check your Note of Contract or ask. As for the lender turning up at a new workplace: the Registry of Moneylenders says approaching a debtor at home or at work to collect a debt does not necessarily constitute an offense, but debt collectors cannot resort to vandalism, violence, or threatening words or behavior. MinLaw’s Professional Service Handbook for licensed moneylenders also lists persistently pestering a borrower at work, in a way that may affect their job performance, as an unprofessional debt-recovery practice. The weeks before you leave are the time to settle or agree a plan With the loan still in force after you go, the weeks before you leave Singapore are when you can do the most about it. Contact your licensed moneylender early, ask how much it would take to close the loan, and either repay it in full or agree in writing how the rest will be paid. Work through these before your last working day: Tell your lender when your job or pass ends. Ask for a settlement figure: the exact amount needed to close the loan on a set date. Repay in full if you can. If not, agree in writing how, and by whom, the remaining installments will be paid. Collect your documents (see below). Give the lender contact details that will still work once you are overseas. Repaying early reduces the interest you pay A licensed moneylender in Singapore must calculate interest on the principal remaining after your repayments, so settling early leaves less principal, or none, for future interest. As of September 2026, the permitted fees on an ordinary personal loan do not include an early repayment fee; the Moneylenders Rules provide for an early redemption fee only on business loans. MinLaw’s Professional Service Handbook also encourages early-repayment incentives such as interest or fee rebates. Your documents are your proof of payment Licensed moneylenders in Singapore must explain your loan terms in a language you understand and give you a copy of the Note of Contract. As of September 2026, they must also issue a receipt for every repayment and a statement of account at least once every January and July. When a loan is settled in full, MinLaw’s Professional Service Handbook says the lender should issue a statement confirming all dues are paid and the account is closed. Keep photos of these on your phone and copies in your email, so you can reach them from anywhere. Payments after you leave need to be agreed before you go If installments will fall due after you leave Singapore, agree the details with your lender while you can still visit the office: whether a family member here can pay on your behalf, which overseas payment methods are accepted, and how receipts will reach you. Get it in writing. If you can’t repay in full, the law limits what you can be charged If your pass will end before the loan is repaid, speak to your licensed moneylender before you miss an installment. The Registry of Moneylenders cannot restructure a loan, because it is a private contractual matter, but you can negotiate with the lender directly or through an intermediary such as a lawyer or a social service agency. Meanwhile, the law caps what you can be charged. Interest and fees are capped by law Charge Legal maximum for licensed moneylender loans to individuals (as of September 2026) Interest 4% per month, on the principal remaining after repayments Late interest 4% per month, only on the amount repaid late Late fee S$60 for each month of late repayment, however
Banner showing two people looking at a screen on a dark blue gradient background, titled 'Secured vs Unsecured Loans in Singapore' with 'What’s the difference?' subtitle.
secured loan Singapore

Secured vs Unsecured Loans in Singapore: What’s the Difference?

Before you borrow from a licensed moneylender in Singapore, it helps to know which of two kinds of loan you are looking at. A secured loan is backed by an asset you pledge as collateral, such as property. An unsecured loan does not need a specific asset to be pledged. For loans from licensed moneylenders in Singapore, the biggest legal difference between the two is the borrowing limit. As of September 2026, unsecured loans are capped by your income, while secured loans have no borrowing cap. Licensed moneylenders are regulated by the Registry of Moneylenders under the Ministry of Law (MinLaw). This article looks at how each type works, how much you can borrow, what each can cost, and what is at stake if repayments slip. It ends with three questions to help you decide which, if either, suits you. How secured and unsecured loans work A secured loan in Singapore requires you to pledge an asset, such as property, as collateral. The asset is the lender’s security: if the loan is not repaid, it can be repossessed and sold. An unsecured loan works differently. It does not require a specific asset to be pledged, and approval rests on the lender’s assessment of your income, existing loan commitments and ability to repay. From licensed moneylenders, unsecured loans are limited by income-based caps, while secured loans have no borrowing cap. One thing does not change between the two. As of September 2026, the same 4% monthly interest cap applies to both. The table below sets the two side by side. Secured vs unsecured loans at a glance (as of September 2026) Secured loan Unsecured loan Collateral An asset, such as property, is pledged No specific asset is pledged Borrowing cap No cap S$500 to 6× monthly income, depending on income and residency, across all licensed moneylenders Maximum interest 4% per month 4% per month Maximum late interest 4% per month, on the overdue amount only 4% per month, on the overdue amount only Maximum late fee S$60 per month of late repayment S$60 per month of late repayment Maximum administrative fee 10% of principal, when the loan is granted 10% of principal, when the loan is granted Total-charges cap Interest, late interest, admin fee and late fees together cannot exceed the principal Same MLCB credit report Checked before the loan is granted Checked before the loan is granted If the loan is not repaid The pledged asset can be repossessed and sold Late charges apply; the lender may make a court claim to recover the debt These figures apply to loans to individuals. Business loans are subject to separate provisions in the Moneylenders Rules. Most rows are identical. The two loan types part ways on collateral, on the borrowing cap, and on what happens if the loan is not repaid, and those differences shape the rest of this article. How much you can borrow without collateral If you are considering an unsecured loan, the first thing to know is your cap. As of September 2026, the total you can owe in unsecured loans across all licensed moneylenders in Singapore combined depends on your annual income and residency status. For Citizens and PRs earning below S$20,000 a year, the cap is S$3,000. For foreigners residing in Singapore, it is S$500 below S$10,000 and S$3,000 from S$10,000 to below S$20,000. At S$20,000 or more, the cap is six times monthly income for both groups. Secured loans have no cap. Annual income Citizens and PRs Foreigners residing in Singapore Below S$10,000 S$3,000 S$500 S$10,000 to below S$20,000 S$3,000 S$3,000 S$20,000 or more 6 × monthly income 6 × monthly income Source: Registry of Moneylenders, as of September 2026. The tiers are set out in Rule 21 of the Moneylenders Rules 2009. The cap is one combined total, not a separate allowance for each lender. Say your cap is S$3,000 and you already owe S$2,000 to one licensed moneylender. Another licensed moneylender could then lend you at most S$1,000 unsecured. Licensed moneylenders check this through the Moneylenders Credit Bureau (MLCB) before granting a loan. In practice, the cap varies widely from one borrower to the next. As of September 2026: A Citizen earning S$3,500 a month (S$42,000 a year) has an unsecured cap of 6 × S$3,500 = S$21,000. A PR earning S$1,500 a month (S$18,000 a year) has a cap of S$3,000. A foreigner residing in Singapore earning S$800 a month (S$9,600 a year) has a cap of S$500. If the amount you need is above your cap, a secured loan from a licensed moneylender may be an option, because secured loans have no cap. That extra room comes with a different kind of cost, covered in the sections that follow. What each type of loan costs It is easy to assume that pledging an asset buys you a cheaper loan. Under the law, it doesn’t. As of September 2026, licensed moneylenders in Singapore can charge at most 4% interest per month on both secured and unsecured loans, regardless of your income. Interest is calculated on the principal still owing after repayments. The rate you are quoted depends on the lender’s assessment. So compare the terms you are actually offered rather than assuming one loan type costs less. Interest is not the only charge, but the list of others is short. Apart from interest, the Registry of Moneylenders allows only these charges (as of September 2026): an administrative fee of up to 10% of the loan principal when the loan is granted late interest of up to 4% per month, only on the amount repaid late a late fee of up to S$60 for each month of late repayment legal costs ordered by a court for a successful recovery claim Interest, late interest, the admin fee and late fees together can never exceed the loan principal. Court-ordered legal costs are separate from this cap. Worked example: the legal maximum cost of a S$3,000 loan These caps are easier to judge in dollars. This

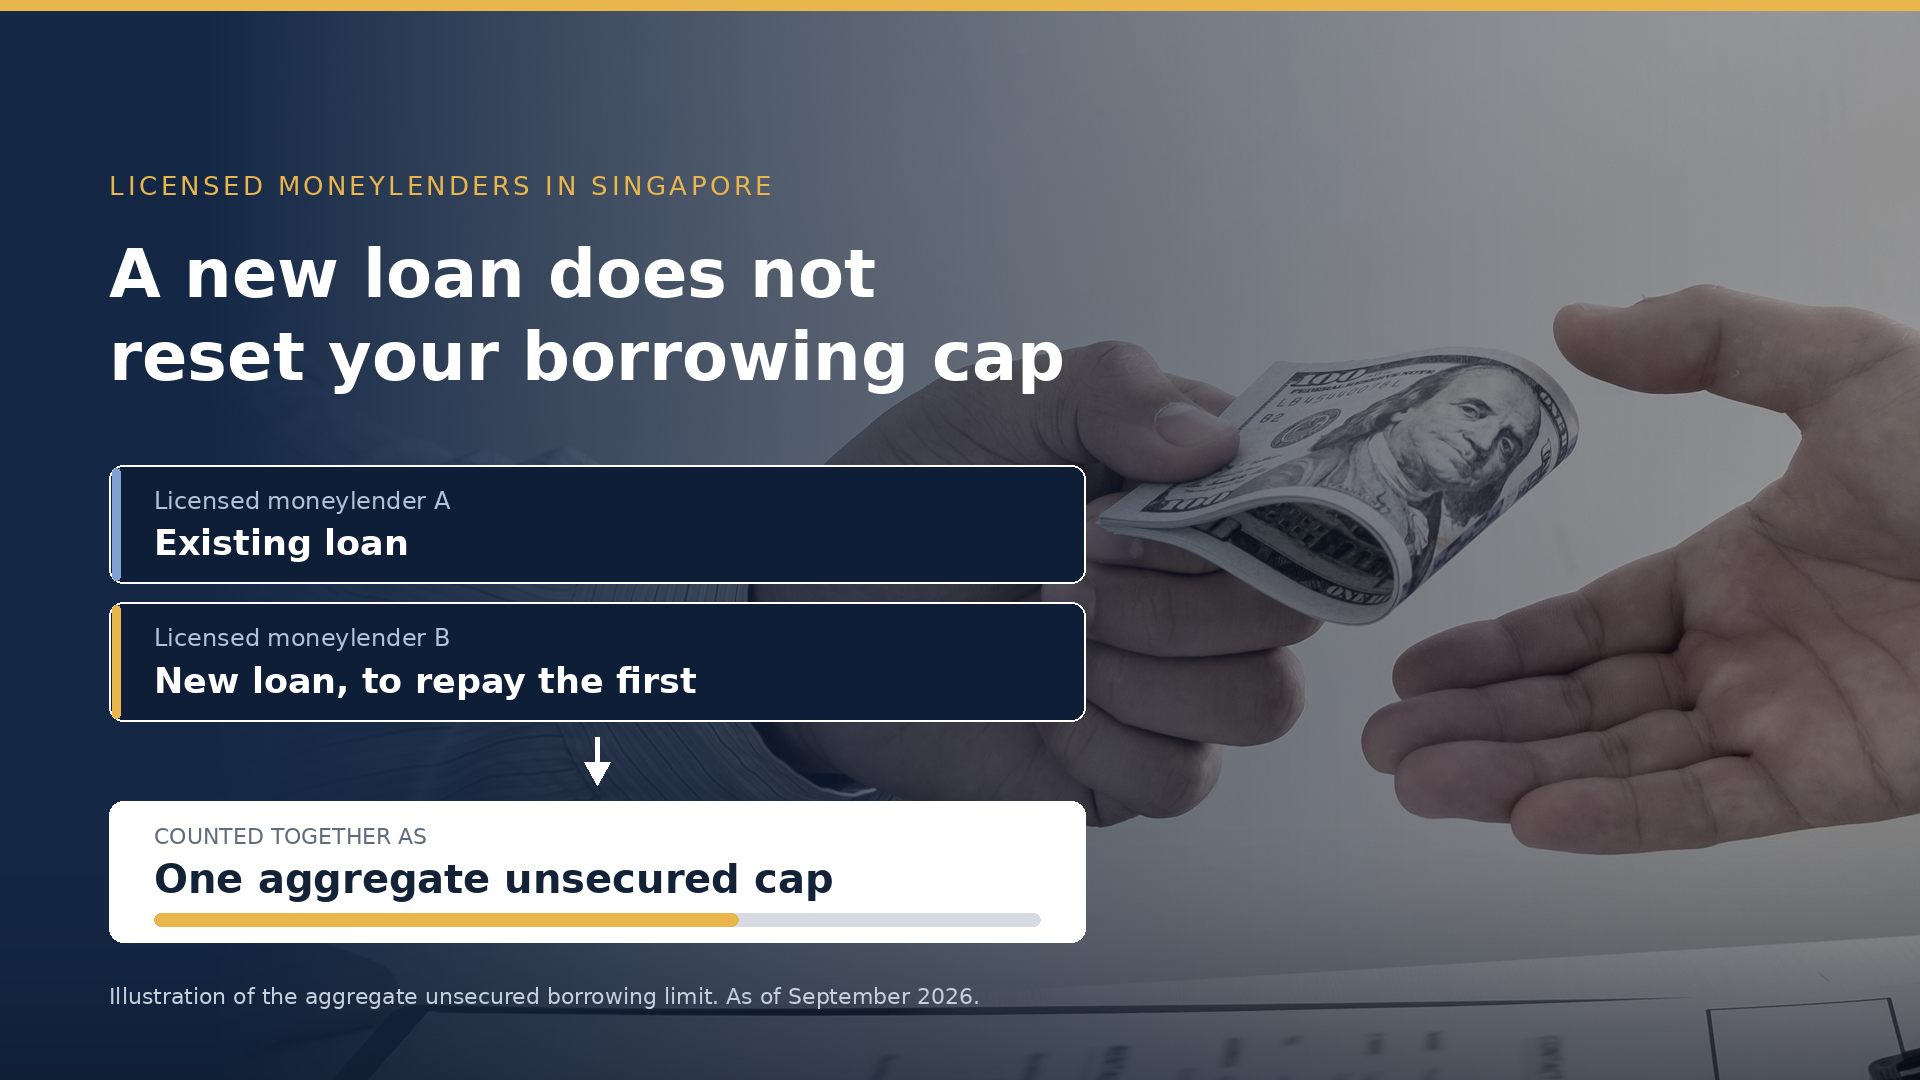
Hero banner showing a borrowing-themed scene: hands exchanging money with the headline 'A new loan does not reset your borrowing cap' and two loan option panels below.
debt consolidation

Can You Take a New Moneylender Loan to Pay Off an Existing Loan?

Yes. There is no blanket prohibition in Singapore on using a loan from a licensed moneylender to repay another licensed moneylender’s loan — the debt consolidation scheme is built around that purpose. What a new loan does not do is give you a fresh borrowing limit. And as of September 2026, the Registrar’s Directions specifically tell licensees not to use a re-loan from the same lender to reset your borrowing cost. Here is how the limits, the cost, and the rules work. Can you take a new moneylender loan to pay off an existing loan? Yes, subject to the borrowing limits. Licensed moneylenders in Singapore can lend you money that you then use to repay an existing loan, and the Ministry of Law’s debt consolidation scheme is defined around exactly that purpose. What does not change is the ceiling: everything you owe across all licensed moneylenders counts towards one aggregate cap. Approval is subject to the lender’s assessment of your income, existing loans, and repayment ability. Is it legal in Singapore to borrow from one licensed moneylender to repay another? Yes, and the regulatory framework contemplates it. The Registry of Moneylenders’ Professional Service Handbook for Licensed Moneylenders (Version 3.1, dated 13 August 2026) defines a debt consolidation loan as “a loan granted by a licensed moneylender under the debt consolidation scheme to a borrower for the purpose of enabling the borrower to repay all outstanding debts owed by the borrower to all licensed moneylenders”. There is no blanket ban. What still applies are the aggregate borrowing limits, the lender’s assessment, the rules on excluded persons, and the restriction on same-lender re-loans set out next. Can the same moneylender give you a new loan to clear the one you already owe them? Not where it resets your borrowing cost. Registrar’s Directions No. 1 of 2026, effective 1 April 2026, state that licensees “should not grant loans or ‘re-loans’ to borrowers to reduce or extinguish an existing debt owed to the same licensee such that this serves to ‘reset’ the total borrowing cost charged, as this is tantamount to deliberately circumventing rules 11, 12 and 12A of the Moneylenders Rules 2009”. Paragraph 1.3 of the same Directions lists as an undesirable practice “offering loans or ‘re-loans’ to pay off existing loans when borrowers are unable to fully pay sums that are due, and charging the borrowers a 10% ‘administrative fee’ repeatedly to roll over the existing loan”. Genuine loan restructuring that complies with the Moneylenders Rules 2009 is still permitted. But the Directions state that these practices may be grounds for refusing a licence renewal, or for suspending or revoking a licence. If a lender offers to clear your existing loan with them by writing a new one that starts the cost over, that is the arrangement the Directions target. Ask about restructuring instead. How much can you borrow if you already have outstanding moneylender loans? As of September 2026, the unsecured borrowing cap for licensed moneylender loans in Singapore is an aggregate figure — it applies to everything you owe across all licensed moneylenders combined, not to each lender separately. A Singapore Citizen or PR earning below S$20,000 a year can borrow up to S$3,000 in total. At S$20,000 or more, the cap is six times monthly income. Existing outstanding unsecured principal counts towards it. Unsecured borrowing caps, aggregate across all licensed moneylenders (as of September 2026) Annual income Singapore Citizens and PRs Foreigners residing in Singapore Below S$10,000 S$3,000 S$500 S$10,000 to below S$20,000 S$3,000 S$3,000 S$20,000 or more 6 × monthly income 6 × monthly income For secured loans, the Registry of Moneylenders states you can obtain a loan of any amount. Your existing loans are visible through the Moneylenders Credit Bureau (MLCB), operated by Credit Bureau (Singapore) Pte Ltd as the designated credit bureau, which a licensed moneylender checks when assessing an application. Source: Registry of Moneylenders, FAQs on Borrowing From Licensed Moneylenders. If I’ve joined the MLCB self-exclusion scheme, can I still take a loan to repay my existing one? Generally no, with one exception. Self-exclusion is a voluntary scheme through the MLCB. Singapore Citizens and PRs may choose a minimum period of 1 or 2 years; foreigners have a minimum of 2 years. While you are registered, you generally cannot obtain unsecured loans from licensed moneylenders, except for a debt consolidation loan. What would a new loan to repay an old one actually cost you? As of September 2026, licensed moneylenders in Singapore may charge at most 4% interest per month on the outstanding principal, and at most 10% of the principal as an administrative fee when the loan is granted. Late interest is capped at 4% per month on the overdue amount, plus a fee of at most S$60 for each month of late repayment. These are legal maximums, not the rate any lender quotes. One further limit matters here: total charges — interest, late interest, the administrative fee and late fees combined — cannot exceed the principal. How is 4% monthly interest worked out on a balance that shrinks as I repay? Interest is charged on what is still outstanding, so it falls as the principal comes down. Illustration only, using the legal maximum rate on an S$3,000 loan repaid in six monthly principal instalments of S$500: Month 1: S$3,000 outstanding, interest S$120 Month 2: S$2,500 outstanding, interest S$100 Month 3: S$2,000 outstanding, interest S$80 Month 4: S$1,500 outstanding, interest S$60 Month 5: S$1,000 outstanding, interest S$40 Month 6: S$500 outstanding, interest S$20 Total interest: S$420. Add an administrative fee of up to 10% of the principal at grant (S$300), and borrowing S$3,000 costs up to S$720. This is an illustration calculated from the statutory maximums — not a SuCredit product or quotation. Do I pay the administrative fee again on the new loan? As of September 2026, a licensed moneylender in Singapore may charge an administrative fee of up to 10% of the principal when a loan is granted, so a new

Smiling woman outdoors holding a tablet, next to a dark teal panel with the headline: ‘Can a sole proprietor get a business loan in Singapore?’
business loan

Can a Sole Proprietor Get a Business Loan in SG? | SU Credit

Yes. A sole proprietor can borrow in Singapore, including from a licensed moneylender. What changes compared with a company is who the lender is lending to. When you trade as a sole proprietorship and borrow from a licensed moneylender, you borrow as an individual, and the limits and charges set under the Moneylenders Act apply to you personally rather than to your business name. That one fact shapes how much you can borrow, what it can cost, and who is responsible for repaying it. Can a sole proprietor get a business loan in Singapore? A sole proprietor can apply to a licensed moneylender in Singapore, and licensed moneylenders lend to sole proprietors as individual borrowers. Approval is subject to the lender’s assessment of your income, existing loans and repayment ability. Your unsecured borrowing limit is calculated from your personal annual income, and as of August 2026 that limit is capped under the Moneylenders Act. Licensed moneylenders in Singapore are licensed and regulated by the Registry of Moneylenders, Ministry of Law. A licensed moneylender is not a bank, and the caps, charge ceilings and borrower protections described on this page come from the Moneylenders Act and its Rules rather than from any individual lender’s policy. Who is the borrower when you run a sole proprietorship? Under the Moneylenders Act, a licensed moneylender lends to an individual borrower. If you trade as a sole proprietorship, that individual is you. The caps below therefore apply to you as a person, and across every licensed moneylender you have borrowed from, whatever trade name the money is used for. What do lenders actually look at when a sole proprietor applies? A licensed moneylender in Singapore assesses three things: your income, your existing loans, and your ability to repay. Approval is subject to that assessment. No licensed moneylender can lend you more than the statutory cap for your income tier, however strong the rest of your application looks. Income, as assessed Your income determines your unsecured cap. For a sole proprietor the figure that matters is your assessed personal income, not the total passing through your business account: the cap is set against income, not turnover. What you already owe Licensed moneylenders check applications against the Moneylenders Credit Bureau (MLCB). The unsecured cap is an aggregate figure across all licensed moneylenders combined, so loans you already hold elsewhere reduce what remains available to you. Your ability to repay The third element is whether the repayments fit what you earn. How any lender weighs this is a matter for its own assessment, and no outcome can be promised in advance. Is it harder to get a loan as a sole proprietor than as a Pte Ltd? The structure you trade under does not change the statutory position when you borrow from a licensed moneylender in Singapore: you borrow as an individual, and the caps and charge ceilings under the Moneylenders Act apply to you personally. The practical consequence for a sole proprietor is that the debt is yours, not your trade name’s. If the business slows, the repayment obligation stays with you. Should a sole proprietor take a business loan or a personal loan? For a sole proprietor borrowing from a licensed moneylender, the distinction is thinner than it sounds. A licensed moneylender lends to you as an individual, so the same caps under the Moneylenders Act apply whether you describe the purpose as business or personal. Using the money for your business does not raise your cap, and it does not change the charge ceilings set out below. Is a “business loan” from a licensed moneylender the same as a personal loan? In substance, for a sole proprietor, yes: the borrower is the individual either way. If a lender describes a product to you as a business loan, ask which caps and charges apply, then check them against the figures below. How much can a sole proprietor borrow in Singapore? As of August 2026, if you are a Singapore Citizen or Permanent Resident earning less than S$20,000 a year, licensed moneylenders can lend you at most S$3,000 in unsecured loans in total, across all licensed moneylenders combined. If you earn S$20,000 or more, the cap is six times your monthly income. Foreigners residing in Singapore face lower tiers. Secured loans have no cap. Borrower Annual income Maximum unsecured borrowing Singapore Citizen or PR Below S$20,000 S$3,000 Singapore Citizen or PR S$20,000 or more 6 times monthly income Foreigner residing in Singapore Below S$10,000 S$500 Foreigner residing in Singapore S$10,000 to below S$20,000 S$3,000 Foreigner residing in Singapore S$20,000 or more 6 times monthly income Any borrower, secured loans Any No cap Unsecured borrowing caps under the Moneylenders Act, aggregate across all licensed moneylenders. Figures as of August 2026, from the Registry of Moneylenders, Ministry of Law. If I already have loans with other licensed moneylenders, how much more can I borrow? The cap is a total, not a per-lender allowance. As of August 2026, the unsecured limit for your income tier applies across all licensed moneylenders combined, and applications are checked against the Moneylenders Credit Bureau (MLCB). If you are already at your cap, a further unsecured loan from another licensed moneylender is not available to you. What is the maximum a licensed moneylender can charge me on top of what I borrow? As of August 2026, a licensed moneylender in Singapore may charge at most 4% interest per month, computed on the principal remaining after repayments. Late interest is capped at 4% per month and applies only to the amount repaid late. The late fee is capped at S$60 for each month of late repayment, and the administrative fee at 10% of the principal, charged when the loan is granted. Interest, late interest, the administrative fee and late fees added together can never exceed the principal you borrowed. Court-ordered legal costs are the only other charge a licensed moneylender may impose. The 4% monthly ceiling has been in effect since 1 October 2015 and

Su Credit, 175 Bencoolen Street #01-36 Burlington Square, Singapore, 189649 Tel: +65 6636 5644