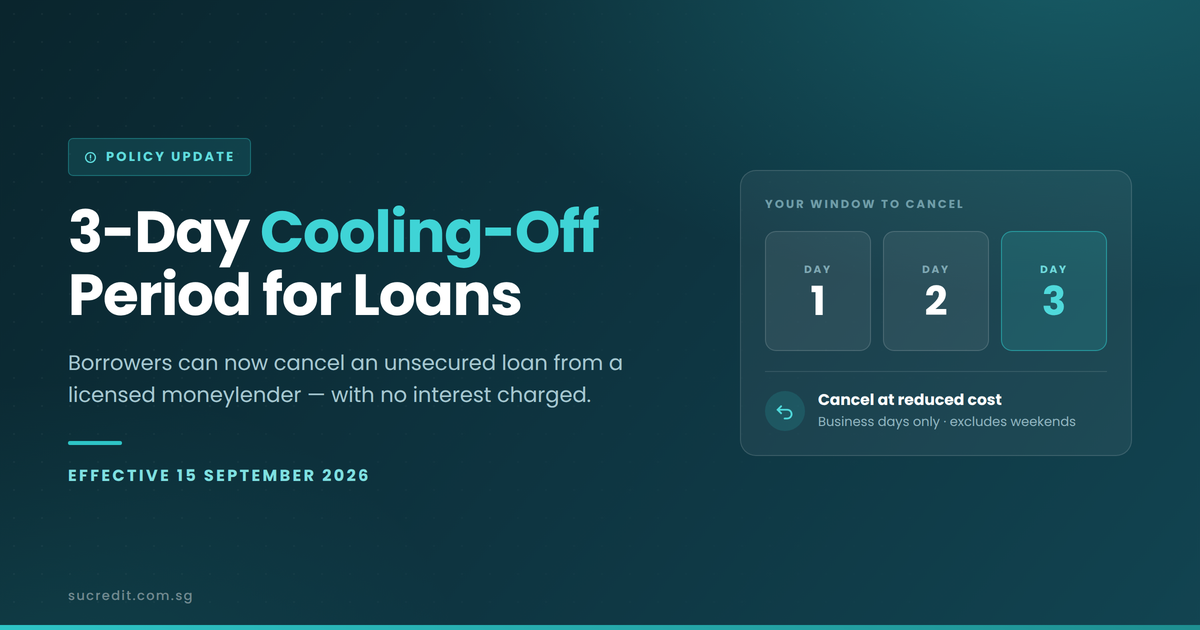
Borrowers in Singapore now have a second chance to reconsider an unsecured loan. From 15 September 2026, every unsecured loan taken from a licensed moneylender comes with a mandatory three-business-day cooling-off period, during which the borrower can walk away from the loan at a sharply reduced cost.
The framework was announced by the Ministry of Law (MinLaw) on 31 August 2026 and developed in consultation with the Credit Association of Singapore, the professional body representing licensed moneylenders. Business loans are the one exception — the cooling-off period applies to all other unsecured loans from licensed moneylenders.
How the Three Days Are Counted
Only business days count. Saturdays, Sundays and Singapore public holidays are excluded, so a loan disbursed on a Friday afternoon leaves the borrower with a window that runs through the following Wednesday rather than expiring over the weekend.
What Changes If You Cancel
This is the part that matters most in practical terms.
Under the previous position, a moneylender could keep the entire loan approval fee plus any interest that had accrued, even if the borrower changed their mind almost immediately. Cancelling was therefore an expensive decision.
From 15 September 2026, a borrower who cancels within the cooling-off period pays no interest at all, and the lender may keep only a capped slice of the loan approval fee.
Loan of $5,000 or below $50 The most the lender may retain — and never more than the approval fee actually charged. | Loan above $5,000 3.5% Of the loan principal — and never more than the approval fee actually charged. |
Maximum portion of the loan approval fee a licensed moneylender may retain on cancellation. Business loans are excluded from the cooling-off framework.
Two safeguards sit on top of those caps. The lender can never retain more than the approval fee it originally charged, and the total amount you repay can never exceed the principal amount of the loan.
A $1,000 loan with a 10% approval fee
Amount that reaches the borrower
Approval fee the lender may retain
Interest charged
The same arithmetic applies to larger loans, with the 3.5% cap replacing the flat $50 figure.
Why the Fee Isn’t Refunded in Full
MinLaw has framed the retained portion as compensation for real work already done: the overhead and due diligence a licensed moneylender carries out before approving a loan. The intent is to give borrowers genuine room to reconsider a decision that may have been made under pressure, while keeping licensed lending commercially viable — a balance MinLaw says it will continue to maintain between protecting borrowers and preserving reasonable access to credit from licensed sources.
The 15 September start date was itself chosen to give licensed moneylenders time to adjust their processes and systems. The Registry of Moneylenders, which sits under MinLaw, will continue working with the industry on implementation.
Better Practices the Industry
Is Being Encouraged to Adopt
Separately, in April 2026 the Registry of Moneylenders updated its Professional Service Handbook for Licensed Moneylenders, encouraging lenders to adopt three borrower-friendly practices:
- Reward good repayment behaviour — discounts or rebates on interest and/or fees for on-time repayments, or for loans settled ahead of schedule.
- Offer digital touchpoints — tools such as an online portal where borrowers can track their own loan servicing.
- Help borrowers in difficulty early — restructuring repayment into something that fits the borrower’s actual financial situation, and/or referring them to a Social Service Agency for support.
These are recommended practices rather than legal requirements, but they are a useful yardstick when comparing lenders.
Confirm the Lender Is Licensed
The cooling-off period exists only in the licensed sector. An unlicensed lender offers none of these protections.
A licensed moneylender operates under the Moneylenders Act, is listed on the Registry of Moneylenders, and must meet you in person at its approved place of business to verify your identity face-to-face before granting a loan.
Source: Ministry of Law, “Mandatory Cooling-off Period for Loans Taken from Licensed Moneylenders”, 31 August 2026 —
This article is a plain-English summary for general information and is not legal advice. SU Credit Pte Ltd is a licensed moneylender in Singapore.